Saving for a Deposit: A Practical Guide for First-Time Buyer Mortgage Applicants
Nov 3, 2026 | By Sophie Carter
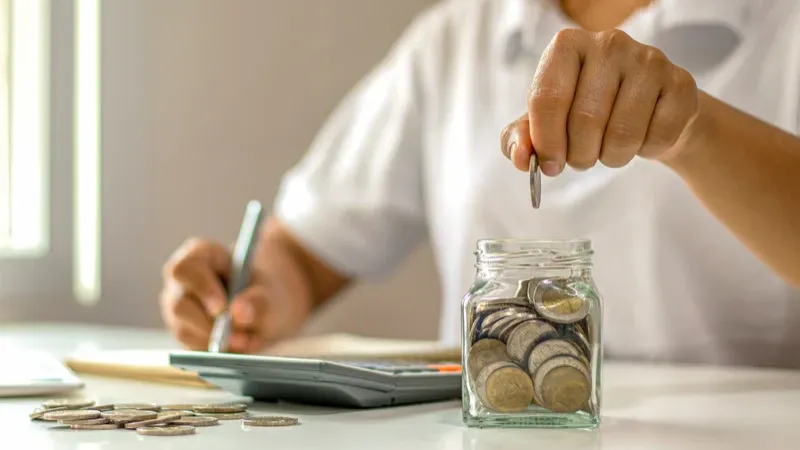
Buying your first home is an exciting milestone, but before you can collect the keys, you'll usually need to save a deposit. For many people, this is the biggest challenge on the journey to homeownership. Whether you're just starting to save or already have money set aside, understanding how to build your deposit can put you in a stronger position when applying for a First-Time Buyer Mortgage and help you achieve your homeownership goals sooner.
 Follow us
 Follow us
Why Is a Deposit So Important?
A mortgage deposit is the amount of money you contribute towards the purchase of your home. The remainder is borrowed from a lender through a mortgage.
Generally, the larger your deposit, the less you'll need to borrow. This can result in:
- Lower monthly repayments
- Access to a wider range of mortgage products
- More competitive interest rates
- Reduced overall borrowing costs
Saving a healthy deposit also demonstrates financial responsibility, which lenders view positively during the mortgage application process.
RECOMMENDED FOR YOU
Set a Realistic Savings Goal
Before you begin saving, it's helpful to understand how much you'll need.
Consider factors such as:
- The average property prices in your preferred location
- Additional purchasing costs, including legal fees and surveys
- Moving expenses
- Emergency savings after your purchase
Having a clear target allows you to monitor your progress and stay motivated throughout your savings journey.
Create a Monthly Savings Plan
Consistency is often more important than saving large amounts occasionally.
Start by reviewing your monthly income and expenditure to identify how much you can comfortably save each month. Setting up an automatic transfer into a dedicated savings account shortly after payday can help make saving a regular habit.
Even modest monthly contributions can build into a substantial deposit over time.
Review Your Spending Habits
Saving for a deposit often involves making small lifestyle adjustments rather than major sacrifices.
Look for opportunities to reduce unnecessary spending, such as:
- Reviewing subscription services
- Eating out less frequently
- Comparing utility and insurance providers
- Reducing impulse purchases
- Creating and sticking to a monthly budget
Redirecting these savings towards your deposit can help you reach your goal more quickly.
Keep Your Savings Separate
Opening a dedicated savings account specifically for your house deposit can help you stay focused.
Keeping your deposit separate from your everyday spending account makes it easier to track progress and reduces the temptation to dip into your savings for non-essential purchases.
Watching your savings grow can also provide additional motivation to continue.
Avoid Taking on New Debt
When preparing for a mortgage application, it's sensible to keep your finances as stable as possible.
Taking out additional loans or building up significant credit card balances may affect your affordability assessment and reduce the amount you can borrow.
Where possible, focus on reducing existing debt while continuing to save for your deposit.
Build a Strong Financial Profile
Saving a deposit is only one part of preparing for a mortgage.
Lenders will also consider your overall financial position, including:
- Your income
- Employment history
- Existing financial commitments
- Credit history
- Regular spending habits
Paying bills on time, managing credit responsibly and maintaining stable finances can all strengthen your mortgage application.
Consider Additional Costs
Many first-time buyers focus entirely on saving their deposit, but it's important to budget for other costs associated with purchasing a home.
These may include:
- Solicitor's fees
- Property surveys
- Valuation fees
- Home insurance
- Moving costs
- Initial furnishing and decorating expenses
Having additional savings available can make your move less financially stressful.
Be Patient and Stay Focused
Saving for a home deposit takes time, and it's normal for progress to feel slow at times.
Setting smaller milestones along the way can help maintain motivation. Celebrate reaching each savings target, whether it's your first £1,000 or another important milestone, while keeping your long-term objective in mind.
Remember that consistent saving is often more effective than trying to save large amounts irregularly.
Seek Professional Guidance Early
Many first-time buyers wait until they have saved their full deposit before seeking advice, but speaking to a mortgage professional earlier can be beneficial.
Understanding how much you may be able to borrow, the documentation you'll need and the mortgage options available can help you set realistic savings goals and avoid surprises later in the process.
Early guidance also allows you to identify any areas of your finances that could be improved before submitting a mortgage application.
Stay Flexible
Your property preferences and financial circumstances may change while you're saving.
Regularly reviewing your savings plan and adjusting your budget where necessary can help keep you on track. Whether your income increases, your expenses change or property prices fluctuate, remaining flexible allows you to adapt your plan without losing sight of your goal.
Final Thoughts
Saving for a deposit is one of the most significant steps towards buying your first home, but with careful planning and consistent effort, it can become much more manageable. By setting realistic goals, following a structured savings plan, managing your finances responsibly and preparing for the additional costs of buying a property, you'll place yourself in a stronger position when the time comes to apply for a mortgage.
Every first-time buyer's journey is different, but staying committed to your savings plan and seeking professional guidance when needed can help turn your dream of homeownership into a reality.
Recommended Stories for You
Team SR Aug 27, 2026
Team SR Jan 5, 2026
Team SR Aug 10, 2026
Team SR Jul 29, 2026
Team SR Jul 6, 2026
Trending Stories
How Caribbean Businesses Are Rethinking Online Sales as Global E-Commerce Changes

When Social Media Doesn’t Work: Multi-channel Marketing for B2B
Building a Trustworthy Sender Reputation From Day One
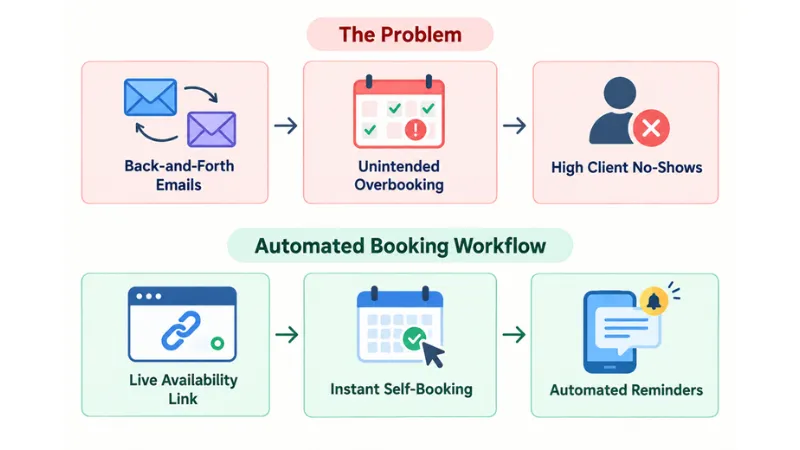
The Best Booking Software for Small Business Owners Who Want to Stop Managing Schedules Manually
What to Ask Before Hiring a Lawyer for a Family Estate Dispute
Buying a Second Hand Car as a Company Vehicle for a Start-Up: Is It a Good Idea
How Startups Can Scale Customer Support Without Growing Their Team
World of Warcraft: Mists of Pandaria Classic – Terrace of Endless Spring Raid Guide