The Small Business Owner’s Guide to Protecting Personal Finances
Oct 26, 2026 | By Sophie Carter
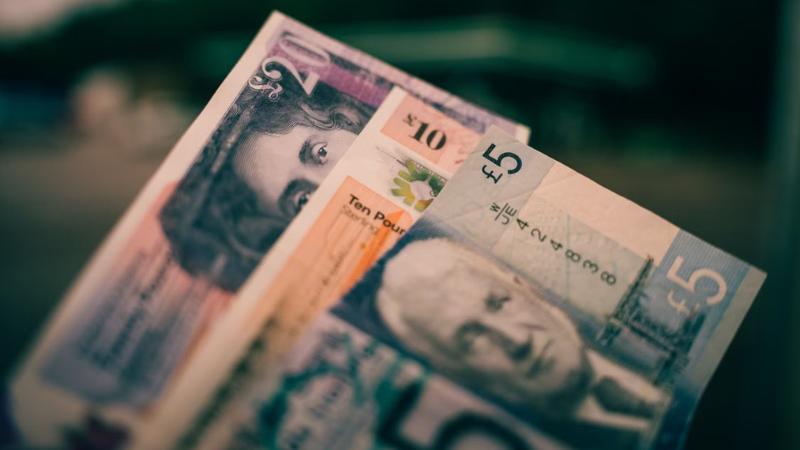
If you’re planning to build a small business, the first few months will expose you to high degrees of risk and volatility. At some point, you will have to pay the bills out of pocket just to keep your business afloat. However, if you’re not careful, you could end up making fatal decisions that will cripple your personal finances. Here are a few tips to help protect your personal money while you focus on running and growing your business.
 Follow us
 Follow us
1. Keep Your Finances Separate
Setting up a dedicated account for your business offers numerous benefits, especially when it comes to tax compliance and revenue tracking. As soon as you launch your brand, create an account through which you can run official transactions and protect your personal money from being the subject of seizures and debt settlements.
You can also apply for a business credit card to start building your enterprise’s credit history, access commercial loans, and avoid confusion in expense/income tracking and auditing activities.
2. Choose the Right Legal Structure
If your business functions as a sole proprietorship at the start, you are responsible for every facet, including financing. This means you will have to absorb all the losses of your business as a result, so it’s important to choose a proper legal structure to ensure compliance and protect your personal finances from the effects of future decisions.
RECOMMENDED FOR YOU
Business Travel Doesn’t Have To Be Overwhelming – Here’s How To Make It Easier
Team SR
Aug 11, 2026
In the United Kingdom, transitioning from being a sole trader to a private limited company, especially if you want to operate your business as a legitimate brand. Keep in mind that you will need to designate yourself as a director and form a board of people with significant control to formalize your designation as a limited company.
3. Build an Emergency Fund
If your business is not yet ready to be designated as a limited company, you must create an emergency fund. Allocate at least six to 12 months of your annual salary from your personal income so you won’t have to pull any funds from your business to cover emergency situations.
Your business must also set aside at least 8% to 10% of its monthly earnings (minus operating expenses) to build a growing buffer. As a result, you will still have enough money to cover essential expenses, deal with the effects of inflation, and even finance your business growth.
If there’s a personal emergency you need to deal with, consider taking out a salary loan if you’re either working full-time or part-time at another company. Make sure that running your enterprise follows the terms of your current employment contract and other pertinent laws. You may want to explore small loans provided by legitimate lenders, such as My Canada Payday if you live in Toronto.
4. Diversify Your Investments
If you rely solely on your business to cover all your financial needs, then you’re exposing yourself to a major setback that’s difficult to recover from. While you run your business, make sure you earn income from other sources to cover your personal needs.
You can try real estate investment trusts, which give you access to profitable properties in the UK, or allocate at most £20,000 of your personal earnings across different vehicles, such as global index funds and high-yield UK Gilts, the yields of which have risen to their highest levels in decades. In any case, a diverse portfolio helps manage risk and ensure that your personal money is adequately protected while you operate your business.
Endnote
If you’re building a business, the risk to your personal finances is always certain. Consider these tips so you can enjoy the fruits of your investment and build a business that’s guaranteed to thrive.
Recommended Stories for You
Team SR Dec 24, 2025
Team SR Sep 23, 2025
Team SR Sep 1, 2026
Sophie Carter Oct 6, 2026

Team SR Jan 15, 2026
Trending Stories
What Startups Should Think About Before Moving Into Their First Commercial Premises
The Filing Was Accepted. The Company’s Interstate Move Is Not Finished.
My Honest RiseGuide Review 2026
How to Check a Neighborhood’s Infrastructure Before You Buy or Rent
Understanding Residential Proxy Networks and How They Protect Online Privacy

When Social Media Doesn’t Work: Multi-channel Marketing for B2B
Warning signs your workplace injury claim is heading for trouble
Simple Ways to Support Your Construction Workers