Expanding Your Business into Turkey: What Startups and International Entrepreneurs Need to Know
Nov 19, 2026 | By Sophie Carter
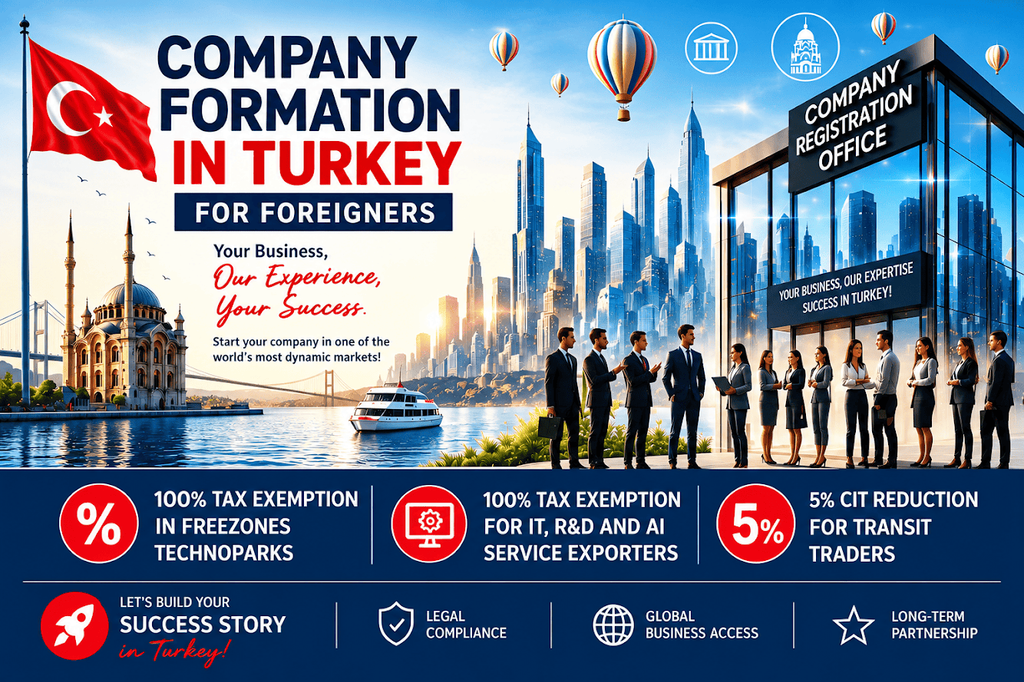
For European startups and international entrepreneurs, expanding into a new market can create significant opportunities for growth. Turkey is one market that deserves consideration, offering access to a large domestic economy and a strategic location connecting Europe, the Middle East, and Asia.
 Follow us
 Follow us
Whether you are launching a technology startup, establishing an e-commerce operation, developing a regional distribution network, or opening a local subsidiary, entering the Turkish market requires more than identifying a commercial opportunity. Understanding the legal framework, company structures, taxation, and regulatory requirements is essential for building a sustainable business.
Here are some of the key considerations for international businesses planning to establish operations in Turkey.
Why Are International Businesses Considering Turkey?
Turkey offers several advantages for companies looking to expand internationally.
RECOMMENDED FOR YOU

- Strategic location: Turkey provides access to markets in Europe, the Middle East, Central Asia, and North Africa. This geographical position can be particularly valuable for businesses involved in international trade, logistics, manufacturing, and distribution.
- Large domestic market: With a population of more than 85 million, Turkey offers a substantial customer base for businesses operating in consumer goods, technology, healthcare, e-commerce, and professional services.
- Developing technology ecosystem: Istanbul and other major Turkish cities have growing startup communities, technology development zones, universities, and innovation-focused businesses. These provide opportunities for technology companies, software developers, and international investors.
- International business connections: Turkey has established commercial relationships with numerous countries and maintains a broad network of international trade and investment agreements.
However, the advantages of entering a new market should always be assessed alongside its legal, financial, and operational requirements.
Can Foreign Entrepreneurs Establish a Company in Turkey?
Yes. Foreign individuals and international companies can generally establish and own 100% of a Turkish company in most sectors. A Turkish business partner is not normally required solely because the shareholders are foreign.
Foreign investors can choose from several legal structures depending on their business objectives:
- Limited Liability Company (LLC): Commonly preferred by foreign entrepreneurs, startups, and small and medium-sized businesses.
- Joint Stock Company (JSC): Often considered for larger investments, more complex corporate structures, and businesses planning future investment rounds.
- Branch Office: Allows an existing foreign company to conduct business activities in Turkey through an extension of its parent company.
- Liaison Office: May be suitable for certain non-commercial activities, such as market research and representation, subject to regulatory approval.
The appropriate structure depends on factors such as the number of shareholders, investment size, planned business activities, management arrangements, and future expansion plans.
What Is the Process of Registering a Company in Turkey?
Although the incorporation process has been modernized through digital systems, foreign investors must still complete several legal and administrative procedures.
1. Selecting the company structure
The investor should determine whether an LLC, JSC, branch office, or liaison office is the most suitable option.
2. Preparing incorporation documents
The required documentation may include passports, shareholder information, company details, powers of attorney, and corporate documents for foreign legal entities. Depending on the country of origin, notarization, apostille or legalization, and certified Turkish translations may be necessary.
3. Determining share capital and ownership
The shareholders must establish the company's capital structure and ownership percentages. The statutory minimum capital for a Turkish LLC is TRY 50,000, while the minimum for a JSC is TRY 250,000. These amounts represent company capital rather than professional incorporation fees.
4. Registering with the Trade Registry
The company's Articles of Association are prepared through the MERSIS system, and the incorporation application is submitted to the relevant Trade Registry Office.
5. Completing tax registration
Following incorporation, the company must complete the relevant tax registration procedures. Depending on its activities, it may also need VAT and withholding tax registrations.
6. Arranging banking and post-incorporation procedures
The company should arrange its corporate banking facilities, accounting system, electronic tax applications, and other administrative requirements.
For a more detailed explanation of the legal structures, required documents, registration stages, and costs, international entrepreneurs can consult this practical guide to company registration in Turkey.
What Should Startups Consider Before Entering the Turkish Market?
Company incorporation is only one part of establishing a successful operation. Startups should consider several additional issues before commencing commercial activities.
1. Taxation and Accounting
Companies operating in Turkey must comply with local accounting and tax legislation. Depending on their activities, obligations may include corporate income tax, VAT, withholding tax, statutory bookkeeping, and periodic tax declarations.
International businesses should also consider the potential implications of double taxation agreements, cross-border transactions, transfer pricing, and withholding taxes when structuring their operations.
Establishing an appropriate accounting and reporting system from the beginning can help prevent compliance problems and provide management with reliable financial information.
2. Employment and Payroll
Companies planning to recruit employees in Turkey must comply with Turkish labour and social security legislation.
This includes employment contracts, payroll calculations, income tax deductions, social security contributions, and statutory reporting to the Social Security Institution (SGK).
Foreign entrepreneurs intending to work in Turkey should also distinguish between company ownership and work authorization. Establishing or owning a Turkish company does not automatically grant a foreign shareholder the right to work in the country.
3. Industry-Specific Licences and Approvals
Certain business activities require additional licences, registrations, or regulatory approvals.
For example, financial services, healthcare, tourism, telecommunications, and some logistics activities may be subject to sector-specific requirements.
Startups should identify these requirements before investing significant resources in their Turkish operations.
4. Banking and Financial Planning
Opening a corporate bank account is an important part of establishing a business in Turkey. However, banks apply their own customer due diligence procedures and may request additional information about foreign shareholders, directors, beneficial owners, and the company's business model.
Investors should therefore consider banking requirements early in the incorporation process rather than treating account opening as an automatic consequence of company registration.
Should You Establish a Turkish Subsidiary or Operate Through a Branch?
This decision depends on the company's commercial and legal objectives.
A Turkish subsidiary is a separate legal entity incorporated under Turkish law. It can enter into contracts, employ staff, issue invoices, lease premises, and conduct business independently, subject to applicable regulations.
A branch, on the other hand, is an extension of the foreign parent company and does not have a separate legal personality in the same way as a subsidiary.
For many international startups and businesses planning long-term operations in Turkey, a locally incorporated LLC or JSC may offer a more practical structure. Nevertheless, the decision should be based on the company's intended activities, liability considerations, taxation, and corporate governance requirements.
Professional Support Can Simplify Market Entry
Entering a foreign market involves decisions that can have long-term legal, financial, and operational consequences. Choosing an unsuitable company structure, overlooking licensing requirements, or delaying tax and accounting arrangements can create unnecessary costs and administrative difficulties.
International businesses can benefit from working with experienced local professionals who understand Turkish corporate law, taxation, accounting, payroll, and regulatory procedures.
With proper preparation and professional guidance, foreign entrepreneurs can establish their Turkish operations more efficiently and focus on developing their business.
Final Thoughts
Turkey can offer meaningful opportunities for European startups and international businesses seeking to expand into a strategically important market. However, successful market entry requires careful planning beyond the initial company registration.
Understanding the available legal structures, preparing the required documentation, evaluating tax obligations, arranging banking facilities, and planning employment requirements are all important steps.
For international entrepreneurs, the best approach is to assess these matters before incorporation and build a compliant operational structure from the outset.
Recommended Stories for You
Oliver Bennett Oct 31, 2026
Team SR Jul 7, 2024
Team SR Jul 21, 2024
Team SR Jun 12, 2024
Team SR Jun 30, 2024
Team SR Jun 28, 2025
Trending Stories
Leading AI Startup in Europe
Grants From The Government To Start A Business
Unique Business Ideas in Luxembourg
Best Startup Industries In 2024 – 2025
Unique Business Ideas In Amsterdam For 2024
Best AI Content Detector Tools
Best Small Scale Business Ideas in France 2024
Series A Funding NEWS Europe – July 2024